Prescription drugs
Qualifying prescription drugs and related costs may be covered through the HSA.
A Health Spending Account (HSA) gives employees a set amount to use toward eligible health and dental expenses while giving employers greater control over the amount they commit to the benefit.
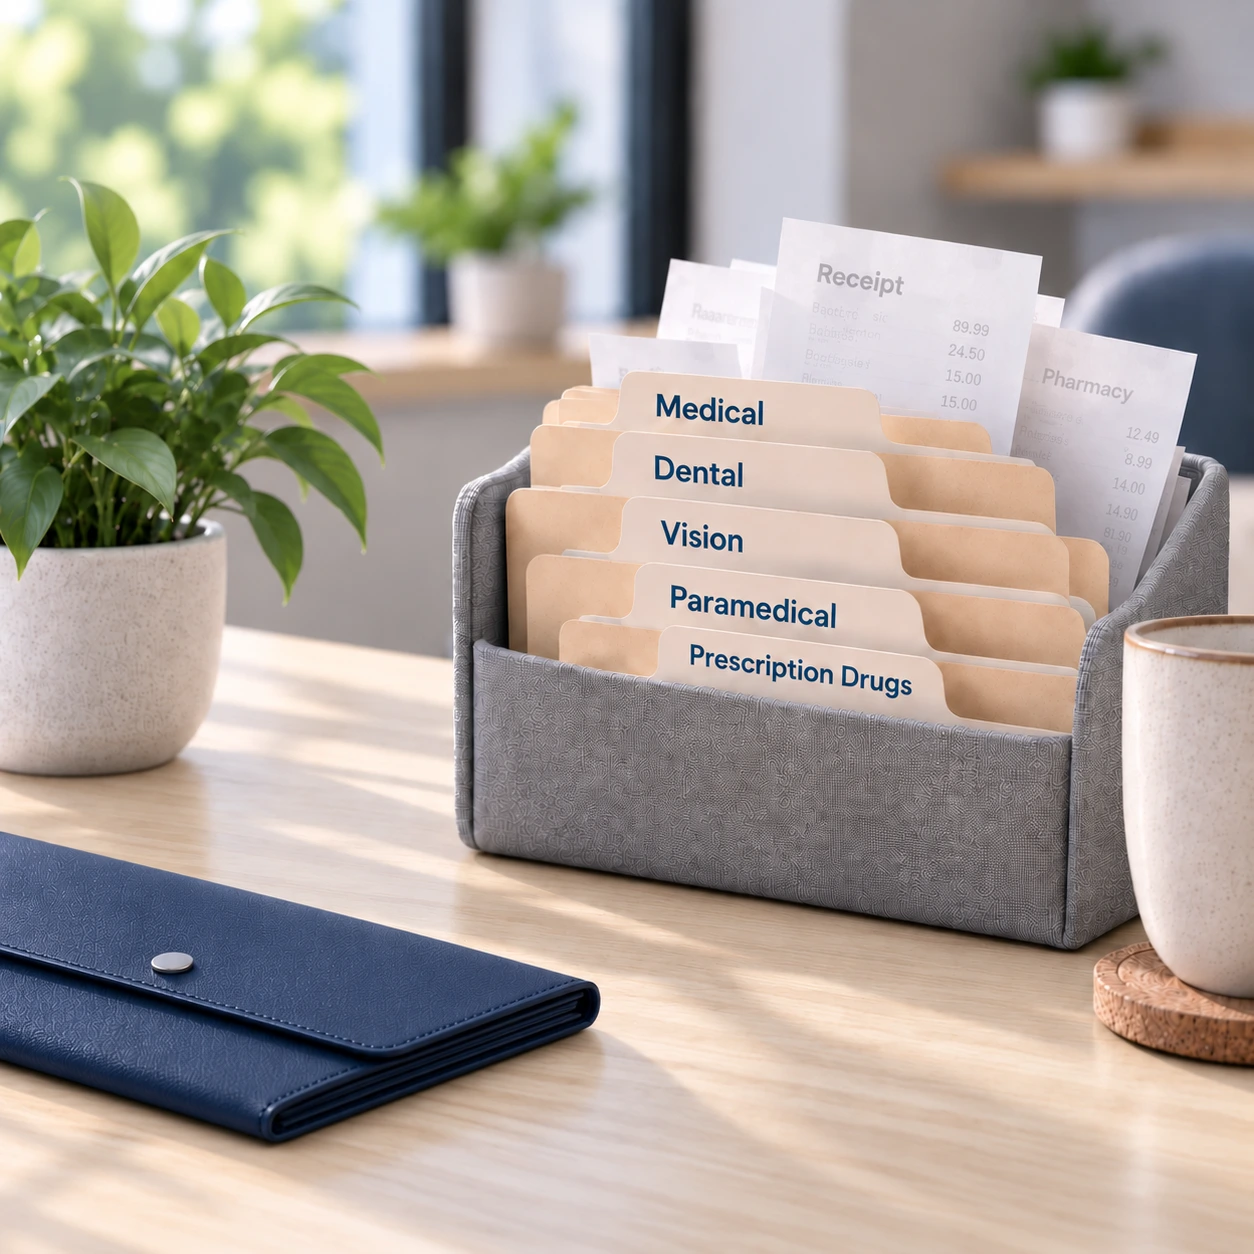
One employee may need prescription eyewear, while another faces dental treatment or physiotherapy costs. An HSA can help with these different expenses without requiring a separate insured benefit for each, provided the claims meet the applicable eligibility requirements.
Employees submit expense details and supporting documents to the administrator, who checks eligibility and determines the amount payable from the account.
Set the amount provided to each employee or defined employee group.
The employee pays a health or dental cost that is not fully covered elsewhere.
The administrator reviews the claim to confirm it meets the applicable HSA and PHSP requirements.
Once approved, the claim is paid from the funds remaining in the employee’s account.
Qualifying prescription drugs and related costs may be covered through the HSA.
Vision-related costs such as eye exams and prescription eyewear may be reimbursed through the HSA.
Eligible dental expenses—including amounts above insured plan maximums or coinsurance levels—may be reimbursable through the account.
Services provided by certain health professionals, such as physiotherapists, chiropractors and psychologists, may qualify under the HSA.
Certain medical devices, equipment and supplies may be covered when they meet CRA requirements.
An HSA can be especially useful for eligible expenses that are only partly covered—or not covered—under the insured health and dental plan, giving employees a flexible way to use employer-funded dollars where they receive the most value.
Before implementing the account, document how it will operate so employees and administrators have a consistent reference for questions and decisions.
Use realistic expense examples to assess how much assistance a proposed allocation would provide over the plan year.
Establish waiting periods, eligible classes, dependent rules and what happens when an employee joins or leaves during the plan year.
Depending on the plan design, unused balances or claims may carry forward for a limited time, subject to applicable PHSP requirements.
Clarify which costs should flow through insured coverage first and where the HSA can supplement the plan.
Choose an administrator based on the tasks your team can manage internally and those it needs the provider to handle.
We clarify what each provider’s quoted fee includes, identify additional charges and explain conditions that could affect the comparison.
Estimate the employer’s expenditure at different claim levels, including administration charges and applicable taxes, and confirm when payments will be required.
Understand what happens to employer funds throughout the arrangement, including when circumstances change.
An HSA’s available balance can be small relative to a major claim. Consider the insured protection employees would retain for expenses beyond the account’s capacity.
Details can vary by provider and plan structure, but the following answers address the questions most often raised by employers.
An HSA gives employees access to employer-funded dollars that can be used to reimburse qualifying health and dental costs, up to the amount available in the account.
No. A Health Spending Account is not a deposit or investment account. It provides access to employer-funded dollars that employees can use for qualifying health and dental costs, subject to the terms of the HSA.
Reimbursable costs are determined by the requirements that apply to Private Health Services Plans. They can include prescription drugs, dental and vision care, paramedical services, and certain medical devices or supplies. Additional conditions or documentation may apply to some items.
Yes. An HSA is often added to existing health and dental coverage to help employees with costs that are only partly covered or fall outside the insured plan.
Some HSA arrangements allow unused balances or claims to carry forward for a limited time. The available approach depends on the plan and should be confirmed with the administrator.
If the HSA qualifies as a Private Health Services Plan, eligible reimbursements are not taxable to employees for federal income-tax purposes. Quebec may treat the employee benefit differently. Employers should confirm the treatment that applies to their plan and employees.
The appropriate amount will vary by employer and should reflect the existing benefits structure, workforce needs, compensation approach and overall budget.
Often yes. Employers may establish reasonable employee classes with different allocations, subject to the administrator's rules and applicable legal and tax requirements.
We can review your existing health and dental coverage, identify where an HSA may add value, and compare available structures, administrators and costs.